Block 01 · 03
Who Is a Financial Professional
Broker, RIA, CFP, CFA, robo-advisor: how they differ, who is required to act in your interest, and what it costs.
The company is up 18% over several months.
Price is only one source. Open the other blocks and see what the full picture is made of.
A decision is rarely built on a single number. A specialist collects scattered information and looks at it as one picture.
In plain words
Large fortunes in the US are never managed alone — behind every one is a team of professionals with access to research and decades of market experience. A financial professional gives you that same level of support on your own account: they read filings, track Fed decisions, prepare recommendations, and explain every decision. You make the calls, armed with a professional view of the market.
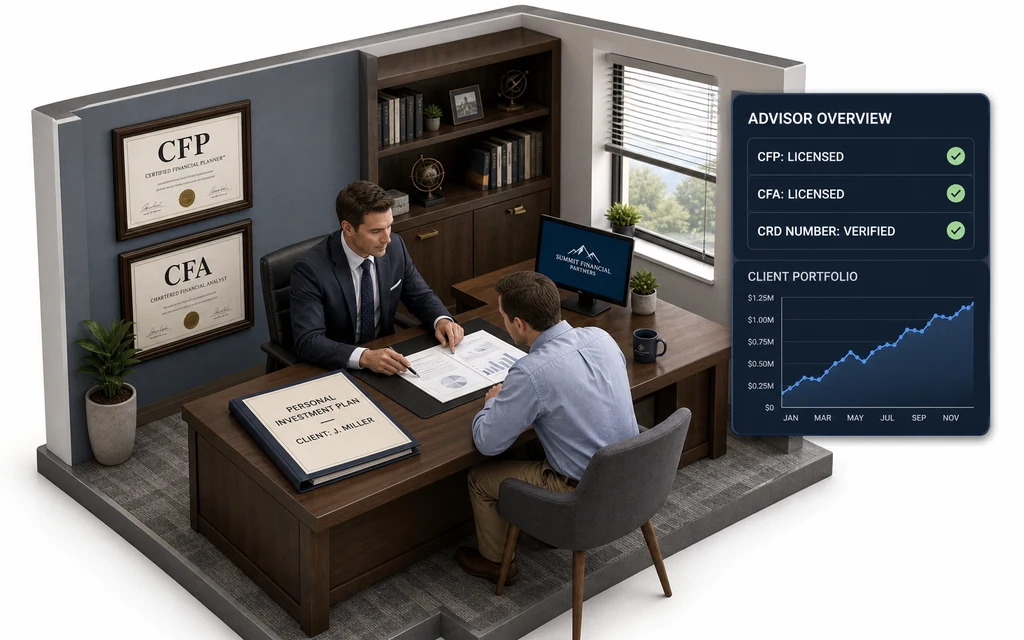
A financial professional is a licensed market expert who works with capital every day. Their license and track record are listed in a public registry, so you know who you're dealing with before the first conversation.
What they do. They break down your situation in numbers — amount, timeframe, goal, tax picture — and build an individual plan: a specific list of instruments and a sequence of actions, not a generic template from the internet.
Why it delivers results. The US market produces data nonstop: quarterly earnings, Fed decisions, oil statistics, IPOs. A professional reads this data daily and spots entry points ahead of time. You don't need to study filings or watch the news feed — you get a ready-made recommendation with an explanation of why it fits right now.
How credentials are verified. The Series 7 and Series 65 exams grant the right to manage client capital. , , and CPA certifications confirm expertise in planning, investment analysis, and taxes. All of this can be checked in public SEC and FINRA databases.
How the relationship works. A written plan, a transparent fee structure, regular portfolio reporting, and 24/7 availability. At any moment you know where your capital is, what's happening with it, and what the next step is. That's the real advantage: institutional-level expertise applied to your personal account.
Common beginner mistakes
- Coordinate decisions with your professional — that's how institutional capital operates
- Define your goal in numbers: amount, horizon, expected outcome
- Follow the individual plan instead of advice from public sources
- Ask questions about every decision — it's the professional's job to explain it all
- Stay in touch: the plan is adjusted alongside the market